1 year fixed
4.59%5.49%
Mortgage solution
A bad inspection report opens three doors, and it is the nature of the defect, not its cost, that decides which one a lender accepts.
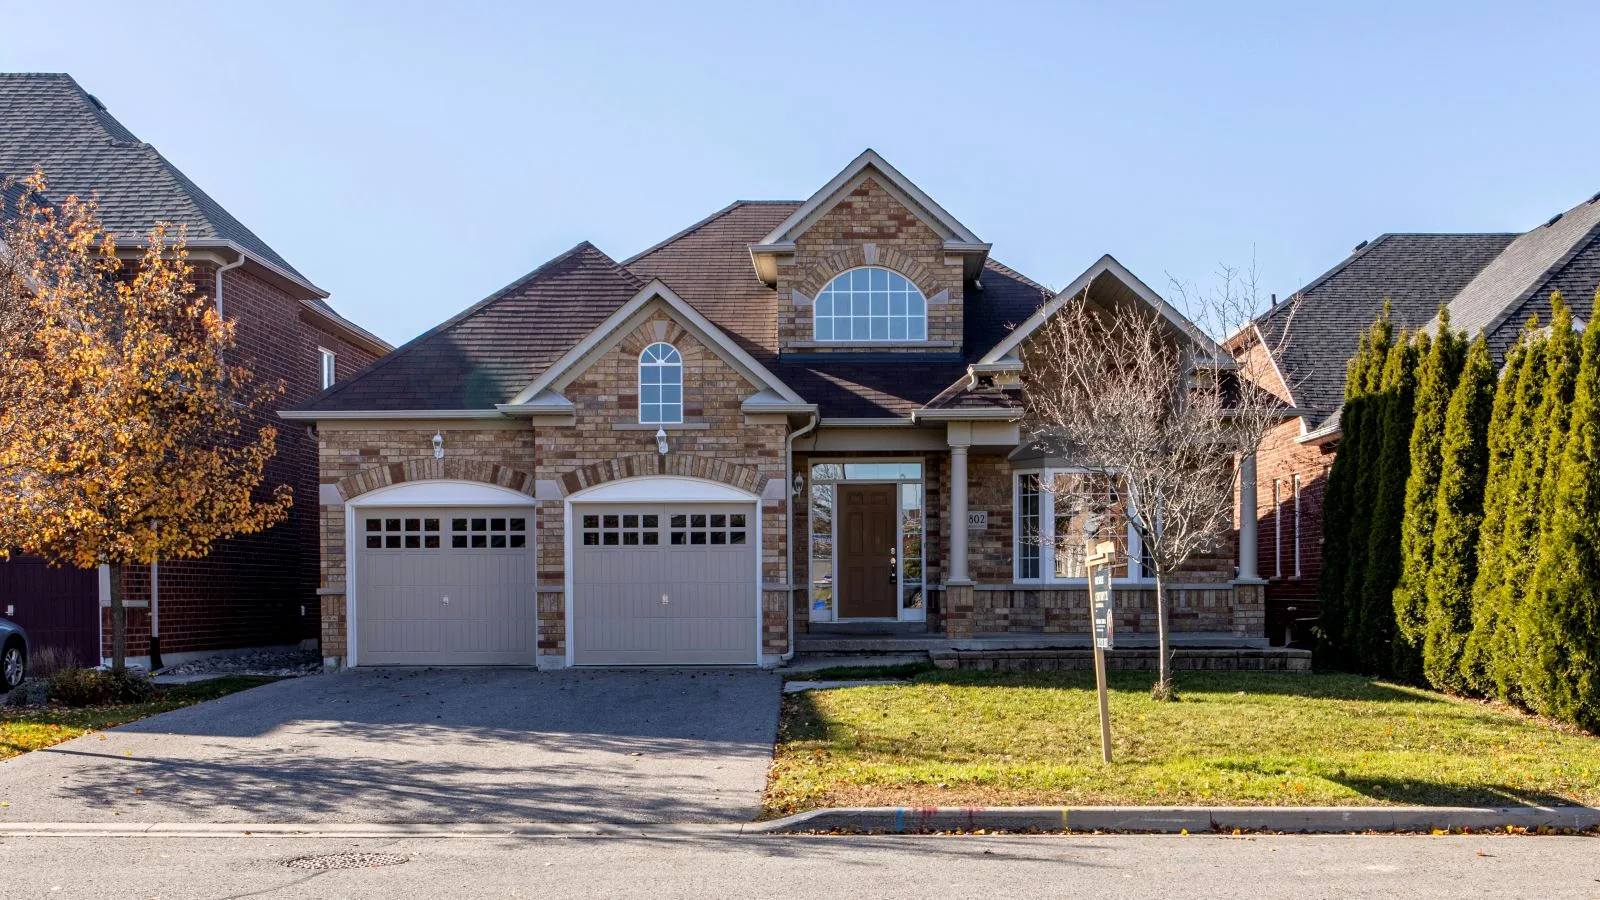
The property gets approved along with the borrower. Type of building, condition and use decide which lenders can take the file, occasionally before your income is even considered.
The full report, quotes for the corrections and the deadline on your inspection condition. Structure, roofing and active water infiltration worry a lender. Cosmetic items don’t.
The mortgage payment is only one piece. Municipal and school taxes, insurance, heating and maintenance are added, and many lenders want a reserve left in your account after closing.
Documents to gather
Yes, when the report flags a structural problem or active infiltration. It can also require the work before disbursement, or hold funds until then. Written quotes let you discuss it in concrete terms.
Your last two notices of assessment, recent pay stubs, an employment letter, three months of bank statements and proof of your down payment. If they are in hand before the offer, a five-day financing condition is workable. If not, weeks get added.
Current rates
These rates are indicative. Yours depends on your file, the type of mortgage (insured or not) and the lender. And look at the penalty too, it matters as much as the number.
5.49%
4.89%
5.95%
5.99%
6.09%
4.45%
Pick the situation closest to yours.
Contact
Buying, renewing, refinancing, or something a bit out of the ordinary: tell us where you’re at, even if it’s still fuzzy. Mathieu gets back to you with next steps and the documents to pull together.