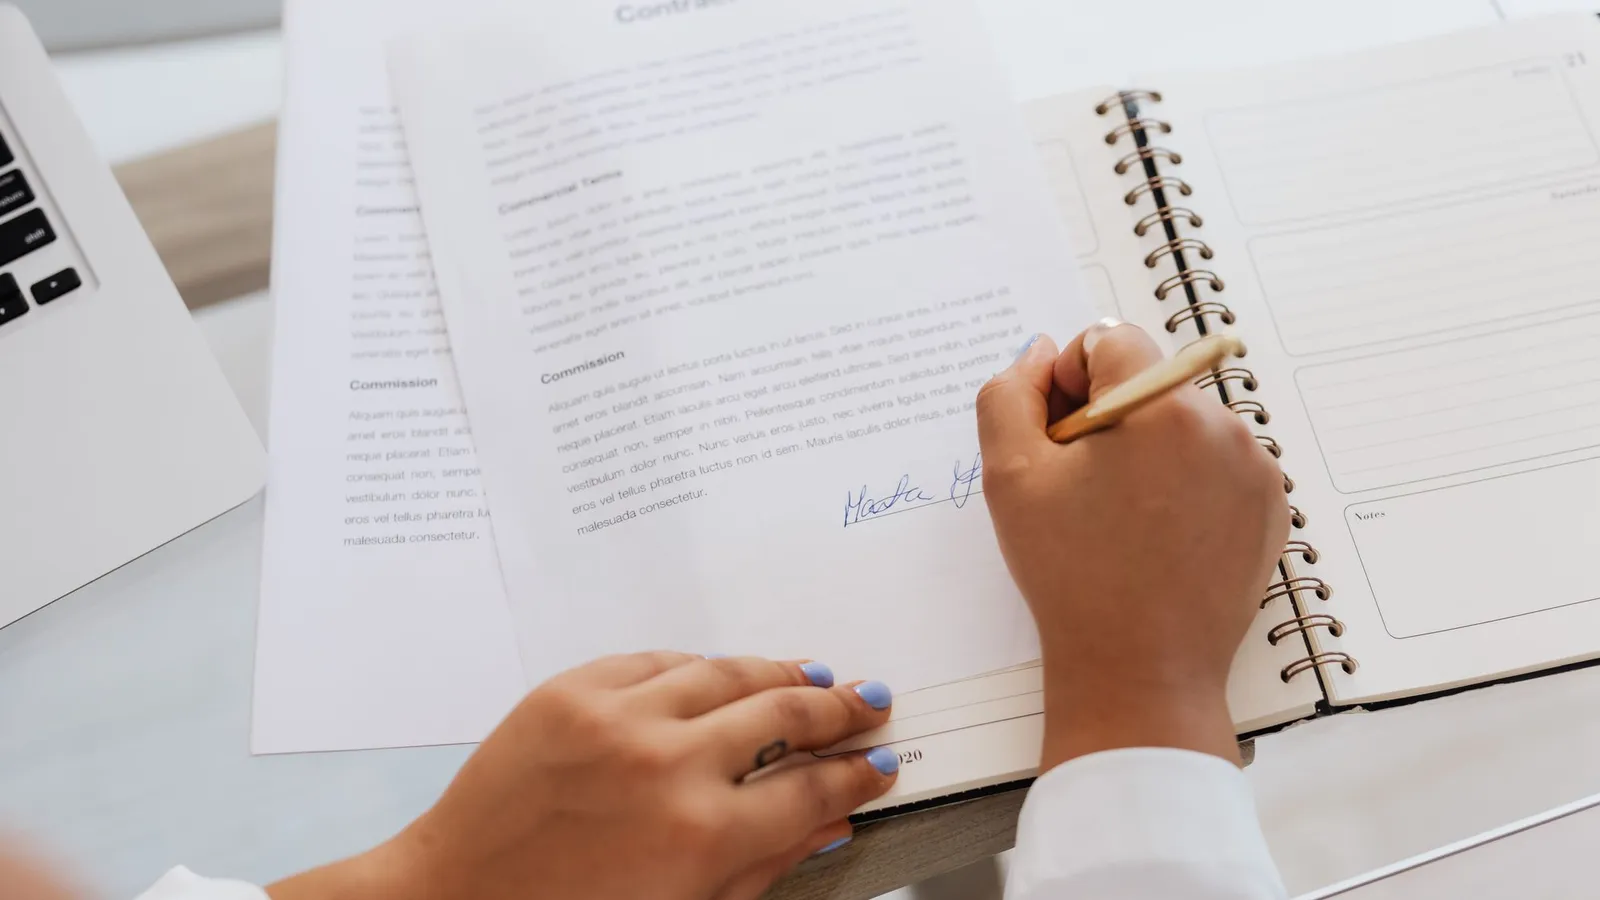
Switching lenders at renewal can force a better offer, or get you a contract that fits you better. Compare the fees, the documents, the timing and the new lender’s conditions before you jump.
Do not look only at the rate
A lower rate can lose its edge if transfer fees, the appraisal or the conditions add too much friction. What counts is the net cost.
And your current lender will often improve its offer once it sees a real comparison on the table.
Prepare documents like a new file
Income, taxes, insurance, mortgage balance, sometimes an appraisal: you may be asked for all of it, like a new file. Wait until the last week and your choices shrink.
Renewal comparison
| Point | Check | Why it matters |
|---|---|---|
| Current lender | Rate, penalty and prepayment rights | Shows the cost of staying. |
| New lender | Transfer fees and conditions | Shows whether switching pays. |
| Next project | Sale, refinance or renovations | Avoids signing a term that blocks the plan. |
Switching goes better when the file is ready well before the deadline.
Read the new contract conditions
Compare the penalty, prepayment privileges, portability and restrictions with your old contract. A transfer should improve on more than the advertised percentage.
Where the file usually needs attention
These bars show which items deserve attention first; they are not a credit score or approval promise.
Rate matters after the full contract is understood.
Penalty can change the real cost of moving.
Prepayment and portability protect future plans.
- ✓Current offer
- ✓Competing offer
- ✓Transfer fees
- ✓Recent documents
- ✓Future penalty
- ✓Prepayment options