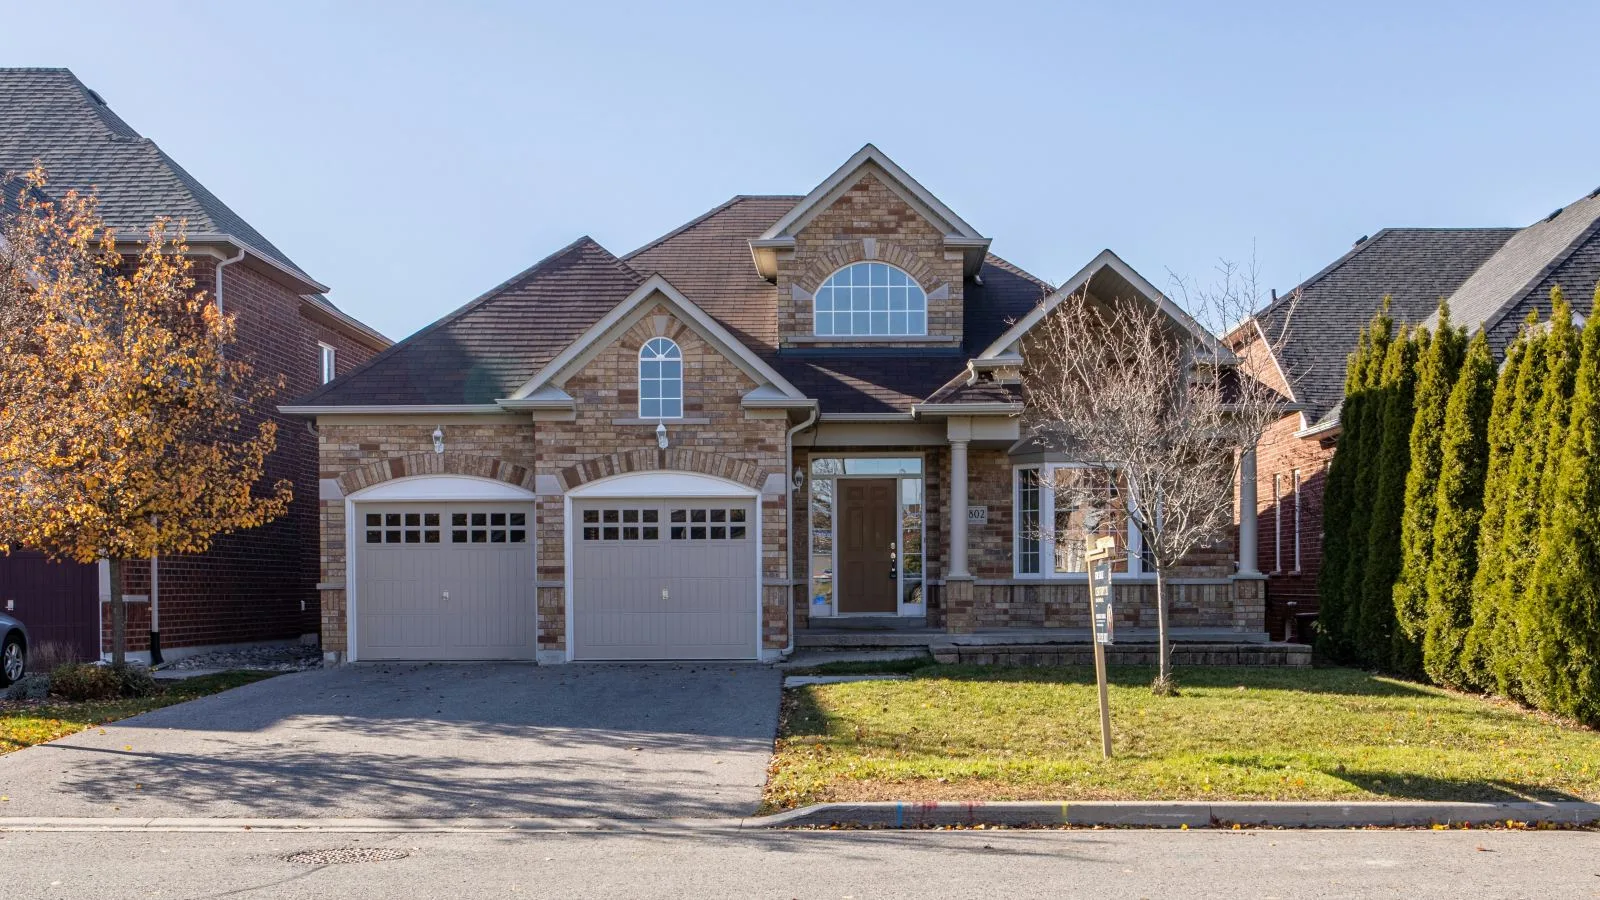
A single-family home often looks simpler than a condo or a plex. That’s half true. There’s still the payment, the taxes, the inspection, the repairs, the insurance and the reserve you have to keep.
Review the full ownership cost
The mortgage payment is only one piece of the budget. Municipal taxes, school taxes, heating, insurance, upkeep, a furnace that’s 25 years old. Add it all up, that’s your real monthly cost.
A cheaper house that needs heavy repairs can end up harder to carry than one that’s been kept up.
Inspection can affect financing
An inspection report can turn up a roof to redo, a foundation crack, a water problem or a system that needs replacing. If it touches the home’s value, the lender will ask questions.
File checkpoints
| Area | Question | Useful proof |
|---|---|---|
| Budget | Does the payment remain affordable after closing? | Payment, taxes and insurance. |
| Timeline | Is the deadline realistic? | Offer, condition and notary dates. |
| Risk | What could slow approval? | Credit, income and property notes. |
Price is one thing. What matters to the lender is the condition of the house.
Keep a reserve for the first months
Paint, appliances, tools, a snow shovel, a repair here and there. It goes fast after you take possession. A reserve calms the budget, and it reassures the lender too.
Where the file usually needs attention
These bars show which items deserve attention first; they are not a credit score or approval promise.
Clean documents reduce back-and-forth.
A realistic condition protects the offer.
Policy fit often matters as much as price.
- ✓Taxes
- ✓Home insurance
- ✓Inspection
- ✓Urgent repairs
- ✓Heating cost
- ✓Reserve after purchase