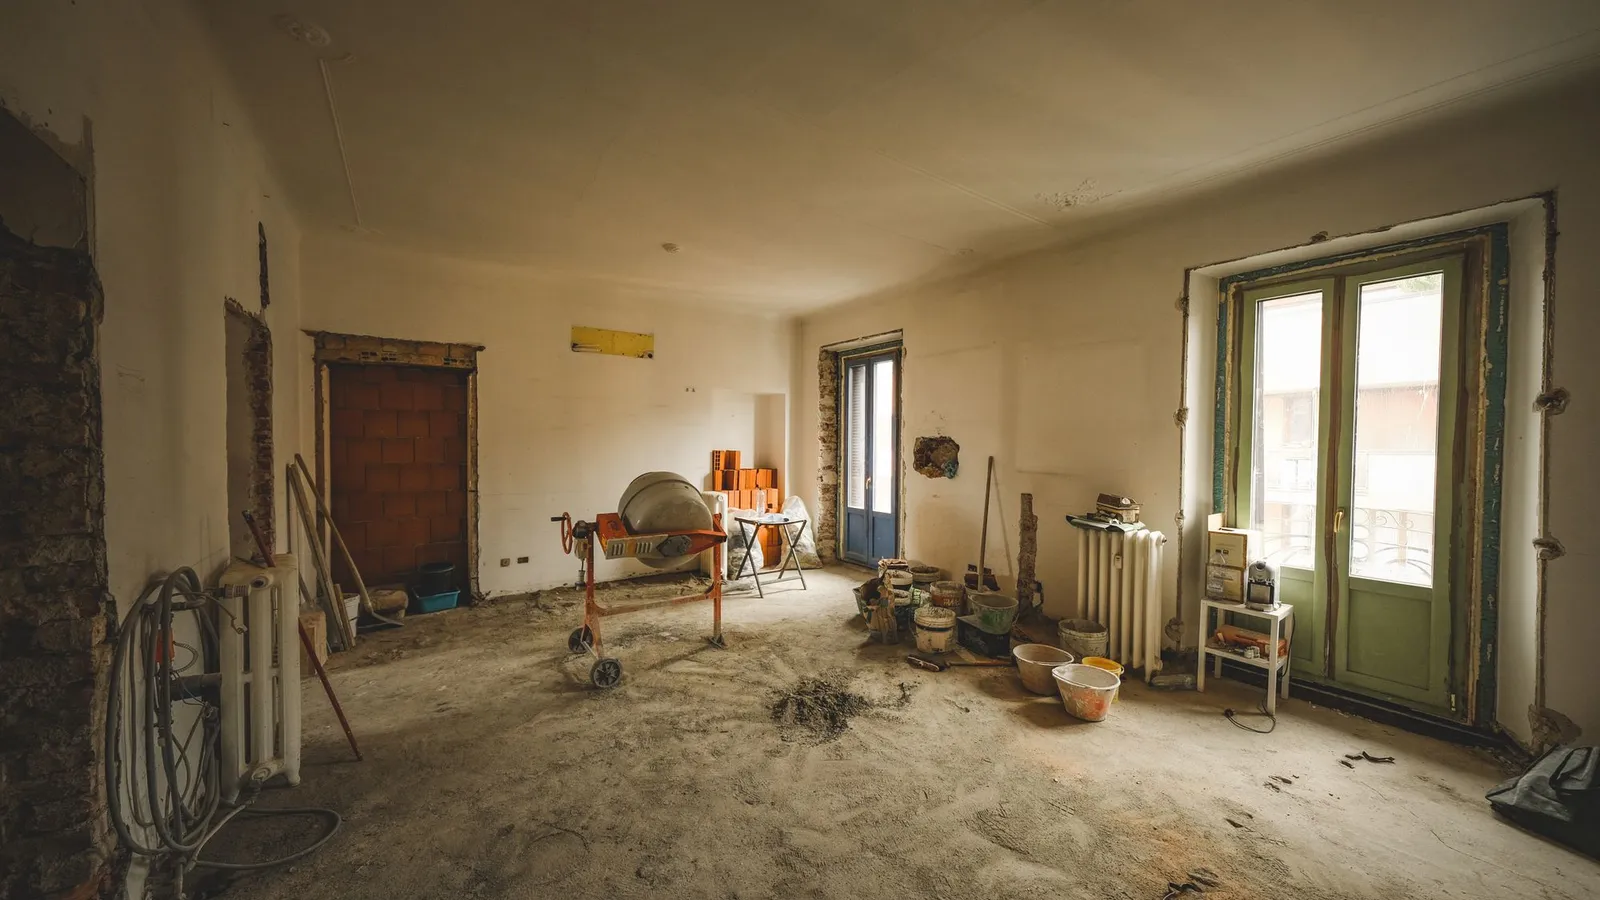
Refinancing to renovate can improve the property and avoid expensive debt. The trap is underestimating the work and signing a loan that doesn’t cover the real project.
Start with a real work budget
The lender and you should both see the quotes, the priorities and the cushion for overruns. A kitchen, a roof and a foundation don’t carry the same risk.
The amount you ask for also has to fit the available equity and the property’s value after review.
Compare payment and added value
The new payment should stay comfortable even if the work costs more. Some renovations add value. Others mainly add comfort.
Refinance checkpoints
| Item | Document | Decision impact |
|---|---|---|
| Balance | Mortgage statement | Confirms equity available. |
| Debts | Statements with rates | Shows what the refinance improves. |
| Project | Quotes or written plan | Prevents borrowing without a clear use. |
A good renovation refinance pays for the work without choking the house.
Track where funds go
Know which work gets paid, in what order, and with what cushion. If the money also repays other debts, the file should say so plainly.
Where the file usually needs attention
These bars show which items deserve attention first; they are not a credit score or approval promise.
Clean documents reduce back-and-forth.
A realistic condition protects the offer.
Policy fit often matters as much as price.
- ✓Quotes
- ✓Available equity
- ✓Priorities
- ✓Overrun room
- ✓New payment
- ✓Work proof